Municipal Bonds: Tax-Advantaged Income
When investors think about bonds, U.S. Treasuries and corporate bonds may be the first investments that come to mind. However, another important part of the bond market helps finance the schools, roads, hospitals, utilities, and other public services we see and use every day.
Our focus this week takes a closer look at these investments—known as municipal bonds, or simply “munis.” Municipal bonds can offer investors a combination of regular income, potential tax advantages, and diversification. They may be particularly appealing to investors in higher tax brackets who are looking for tax-efficient income outside of retirement accounts.
Defining Municipal Bonds
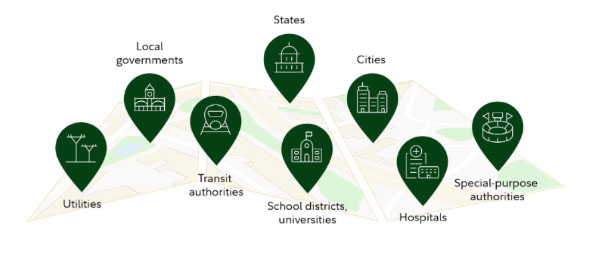
When you purchase a municipal bond, you are essentially loaning money to a state or local government or another qualifying issuer. Municipal bonds are commonly issued to finance public projects such as:
- Schools and universities
- Roads, bridges, and transportation systems
- Hospitals and health care facilities
- Water and sewer systems
- Other public infrastructure and community projects
In exchange for providing the money, the issuer generally agrees to make periodic interest payments and repay the bond's principal—or face value—when the bond reaches its maturity date, assuming the issuer meets its obligations.
Put simply:
You lend money → the issuer pays interest → your principal is returned at maturity.
Municipal bonds typically pay interest semiannually, although payment structures can vary.
Who Issues Municipal Bonds?
Two Common Types of Municipal Bonds
Although the municipal bond market includes many different structures, municipal bonds generally fall into two broad categories.
General Obligation Bonds:
General obligation, or GO, bonds are typically issued by states, cities, counties, or other governmental entities. Repayment is generally supported by the issuer's taxing authority or other available governmental revenues, depending on the specific bond.
For example, a city might issue general obligation bonds to help finance the construction of a new school.
Revenue Bonds:
Revenue bonds are generally repaid from revenues associated with a particular project, facility, or source. A municipality might issue bonds to finance a toll road, for example, and use revenue generated by tolls to help make payments to bondholders.
This distinction matters because investors should understand where the money used to repay a bond is expected to come from.
Why are Municipal Bonds Attractive to Investors?
One of the biggest potential advantages of municipal bonds is their tax treatment. Interest from many municipal bonds is exempt from federal income tax. Depending on the bond and the investor's state of residence, the interest may also be exempt from state and/or local income taxes.
That can make the income generated by municipal bonds particularly attractive to investors in higher tax brackets.
What are the Risks?
Tax advantages don't mean municipal bonds are risk-free. Like other fixed-income investments, munis carry several risks investors should understand.
Interest Rate Risk:
Bond prices and interest rates generally move in opposite directions. When market interest rates rise, the market value of an existing bond will generally fall. When rates fall, existing bond prices will generally rise Longer-maturity bonds tend to be more sensitive to changes in interest rates than shorter-maturity bonds.
Credit and Default Risk:
Municipal issuers can experience financial difficulties.
Credit Risk:
Represents the possibility that an issuer may be unable to make its required interest or principal payments. Although municipal bonds have historically experienced lower default rates than similarly rated corporate bonds in many rating categories, credit quality varies significantly from one issuer and bond to another. An investor should therefore consider the financial strength and creditworthiness of the issuer rather than assuming all municipal bonds carry the same level of risk.
Call Risk:
Some municipal bonds are callable, meaning the issuer has the right to repay the bond before its scheduled maturity date. This often becomes more likely when interest rates decline because an issuer may be able to refinance its debt at a lower interest rate. For the investor, that can mean receiving principal back earlier than anticipated and potentially having to reinvest it at a lower prevailing yield.
Liquidity Risk:
The municipal bond market contains an enormous number of individual securities, and many do not trade frequently. As a result, an investor who wants to sell a particular municipal bond before maturity may find that there are fewer potential buyers or that the price offered is less favorable than expected.
Who Might Consider Municipal Bonds?
Municipal bonds won't be appropriate for every investor, but they may be worth considering for people such as:
- Income-focused investors seeking a source of regular interest income.
- Higher-income investors who may benefit more from federally tax-exempt income.
- Investors who have maximized tax-advantaged retirement accounts and are looking for additional ways to improve tax efficiency within taxable accounts.
- Residents of certain higher-tax states who may benefit from state and/or local tax exemptions on qualifying in-state municipal bonds.
- Retirees and near-retirees looking to incorporate fixed income into a diversified portfolio, depending on their objectives and risk tolerance.
Bottom Line
Municipal bonds can provide an interesting combination of income, potential tax advantages, diversification, and generally lower historical default rates relative to corporate bonds, depending on credit quality.
Their tax advantages can make them especially worth examining for investors in higher tax brackets. However, the appropriate choice depends on much more than the stated yield. Credit quality, maturity, interest-rate sensitivity, call provisions, liquidity, tax treatment, and the investor's overall financial situation should all be considered.
At Lighthouse Wealth Partners, we believe investments should be evaluated as part of your broader financial picture. If you have questions about municipal bonds, taxable bonds, or how fixed income may fit within your portfolio, please never hesitate to contact our team.
Disclosures: This material is provided for informational and educational purposes only and should not be construed as individualized investment, tax, or legal advice or as a recommendation to buy or sell any security. Municipal bonds are subject to risks, including interest-rate risk, credit/default risk, call risk, liquidity risk, and market risk. If a bond is sold before maturity, its market value may be more or less than its original cost. Interest from many municipal bonds is exempt from federal income tax; however, certain municipal bond interest may be subject to federal income tax, the federal alternative minimum tax, and/or state and local taxes. Capital gains, if any, are generally taxable. Tax laws and individual circumstances vary. Investors should consult their tax professional regarding their specific situation. Diversification does not ensure a profit or protect against loss.